Behind on your VA mortgage? You still have options.
A PCS move or a change in income can make your mortgage hard to manage. We help Oʻahu homeowners understand whether a sale or short sale is worth exploring, starting with a free conversation.
Free initial consultation · No obligation
Have a foreclosure notice or sale date? Contact your servicer and an attorney promptly. This form and a short sale request do not pause legal deadlines.
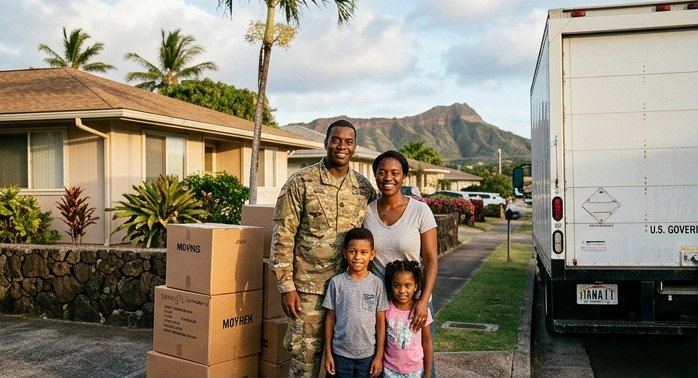
 Proudly serving those who served
 Oʻahu · Hawaiʻi
A short sale is a lender-approved alternative to foreclosure. Start by understanding your options, the costs, and what happens next.
Want to keep the home? Ask your servicer about repayment, forbearance, or modification options before choosing a sale.
What exactly is a short sale?
A short sale is a sale for less than the mortgage debt, with the mortgage holder’s approval. The approval terms should explain the sale and how any unpaid balance will be handled.
For VA loans, this falls under the VA Compromise Sale program — a path the VA built specifically to help service members and veterans exit a home they can no longer afford, without going through foreclosure.
Four myths that keep VA homeowners stuck
Fear and bad information cause many veterans to wait too long. Tap any myth to see what's actually true.
Every situation is different. The points above are general information, not a guarantee — your specific outcome depends on your lender, your loan, and your circumstances. We'll walk you through yours, honestly.
Worried about one of these? Ask us — it's free →How a VA short sale actually works
Most of the heavy lifting falls to us and your lender. Here's the path, from first call to keys handed over.
Free, confidential consultation
We listen to your situation, review your loan and home, and tell you honestly whether a short sale makes sense — with zero obligation.
Request your VA Compromise Sale package
Ask your servicer for its requirements. We help organize the sale documents and coordinate the real estate side of the application.
List at fair market value
We review comparable sales, discuss pricing with you, and market the property. A buyer’s offer still needs the required mortgage-holder approvals.
Submit the offer to your lender & the VA
Once we have a solid offer, we package it with your hardship file and submit everything for review and approval.
Approval — and a plan for the shortfall
Review the written approval with your attorney, including any remaining debt. Confirm VA entitlement and any separate VA debt questions directly with VA before closing.
Close and move forward
Once the required approvals are in place, we coordinate the sale and help you plan closing and your move.
Timing depends on the lender’s review, complete documents, finding a buyer, and any other liens. A closing date cannot be promised. We keep you updated on the sale and outstanding requests.
How it can unfold, week by week
Here's an illustrative timeline for a VA homeowner who's behind on payments and underwater — from the first call to the day they move forward. Every situation differs, but this is the shape of it.
We talk it through
You reach out and we have an honest, confidential conversation about your hardship and your home. No cost, no pressure, no obligation to move forward.
Your case gets started
We help organize the real estate documents and coordinate with CK Capital Management on the servicer’s short sale requirements.
Your home is listed
We prepare a pricing and marketing plan based on current comparable sales and your property’s condition.
A buyer steps up
We secure a solid offer and package it with your hardship file for submission to your lender and, for VA loans, the VA.
The lender & VA decide
CK Capital negotiates directly with your mortgage company, handles the back-and-forth and paperwork, and works toward approval terms.
If approval and closing are completed, the homeowners can plan their move. Debt treatment and future VA entitlement depend on written terms and the VA’s review.
Start your own timeline — free review →Illustrative example only. Timelines and outcomes vary based on your lender, the VA, your loan, and your circumstances; nothing here is a promise of a specific result.
Signs a short sale may make sense
If keeping the home no longer works and selling may leave a shortfall, ask about your options. Your servicer reviews eligibility based on the loan, your finances, and its requirements.
Your servicer will provide a document list and may request information from each borrower. Common requests include the items below. You don’t need a complete package to call us.
Costs to review before you decide.
Some transaction expenses may be paid from sale proceeds if approved. Other balances or a seller contribution may remain. Review the estimated settlement statement, service agreements, and written approval before committing.
These lists are discussion points, not a promise of payment or forgiveness. Ask which items are covered, who pays each cost, and whether any contribution is required.
Not sure where you fit? Let's look together →What it costs
The initial consultation is free. Commissions, closing costs, third-party fees, and any seller contribution depend on written agreements and lender approval. Review those terms before deciding.
Initial review
The initial consultation is free. A short, confidential conversation costs nothing and commits you to nothing. No obligation to move forward.
Commissions and closing costs
Commissions, closing costs, and any seller contribution depend on written agreements and lender approval. Some transaction expenses may be paid from sale proceeds if approved. Other balances may remain.
Third-party fees
CK Capital Management is an independent partner. Their services and fees are subject to separate written terms; review these before engaging them.
These are discussion points, not a promise of payment or forgiveness. Review the estimated settlement statement, service agreements, and written approval before committing.
See where you stand — privately, right here.
Nothing you enter is saved or sent. These tools are just to help you think it through before you reach out.
Answer honestly — there are no wrong answers.
See how a sale could cover your mortgage, other property debt, and selling costs. Start with two amounts, then add details for a fuller estimate.
Use a current payoff estimate if you have one. It may already include interest and lender fees.
Enter what you expect the home to sell for. This calculator does not determine your home’s value.
6% is an editable example, not a quoted fee. Include commissions and other costs you estimate as a percentage.
Add mortgage & cost details Optional
Enter only amounts not already included above. Leave unused fields blank; they count as $0.
Include the amount owed on any additional mortgage or home equity line.
For example, unpaid property taxes or HOA balances that must be settled at closing. Exclude amounts already in a payoff or selling costs.
Add only interest, late charges, or lender fees missing from your mortgage payoff estimates.
Add fixed-dollar escrow, title, repair credits, or other closing expenses not covered by the percentage above.
Enter your primary mortgage payoff and estimated sale price to see the breakdown. A $0 payoff is allowed.
- Estimated sale price
- Selling costs
- Extra selling costs
- Net sale proceeds before debt
- Primary mortgage payoff
- Second mortgage / HELOC
- Other property liens & balances
- Additional interest & lender fees
- Total estimated payoffs
- Estimated break-even sale price
An illustration, not a settlement statement or lender decision. A shortfall is not necessarily an amount you will owe personally. Written approvals determine any remaining obligation.
These tools give general estimates only and are not a determination of eligibility, a home valuation, or any kind of advice. Your actual options depend on your lender, loan, the VA, and your circumstances.
We help FHA and conventional homeowners too.
VA homeowners are our focus, and we also help with FHA, USDA, and conventional short sales. Your lender’s requirements and approval terms depend on your loan.
Let's look at your situation — a free review, no pressure.
Tell us a little about your home and your loan. We'll review it personally and reach out with honest, clear next steps. Please leave out account numbers and sensitive financial documents.
Mahalo — we've got it.
Your information is in. We’ll review your request and contact you to discuss next steps. If a legal deadline is approaching, contact your servicer and attorney directly.
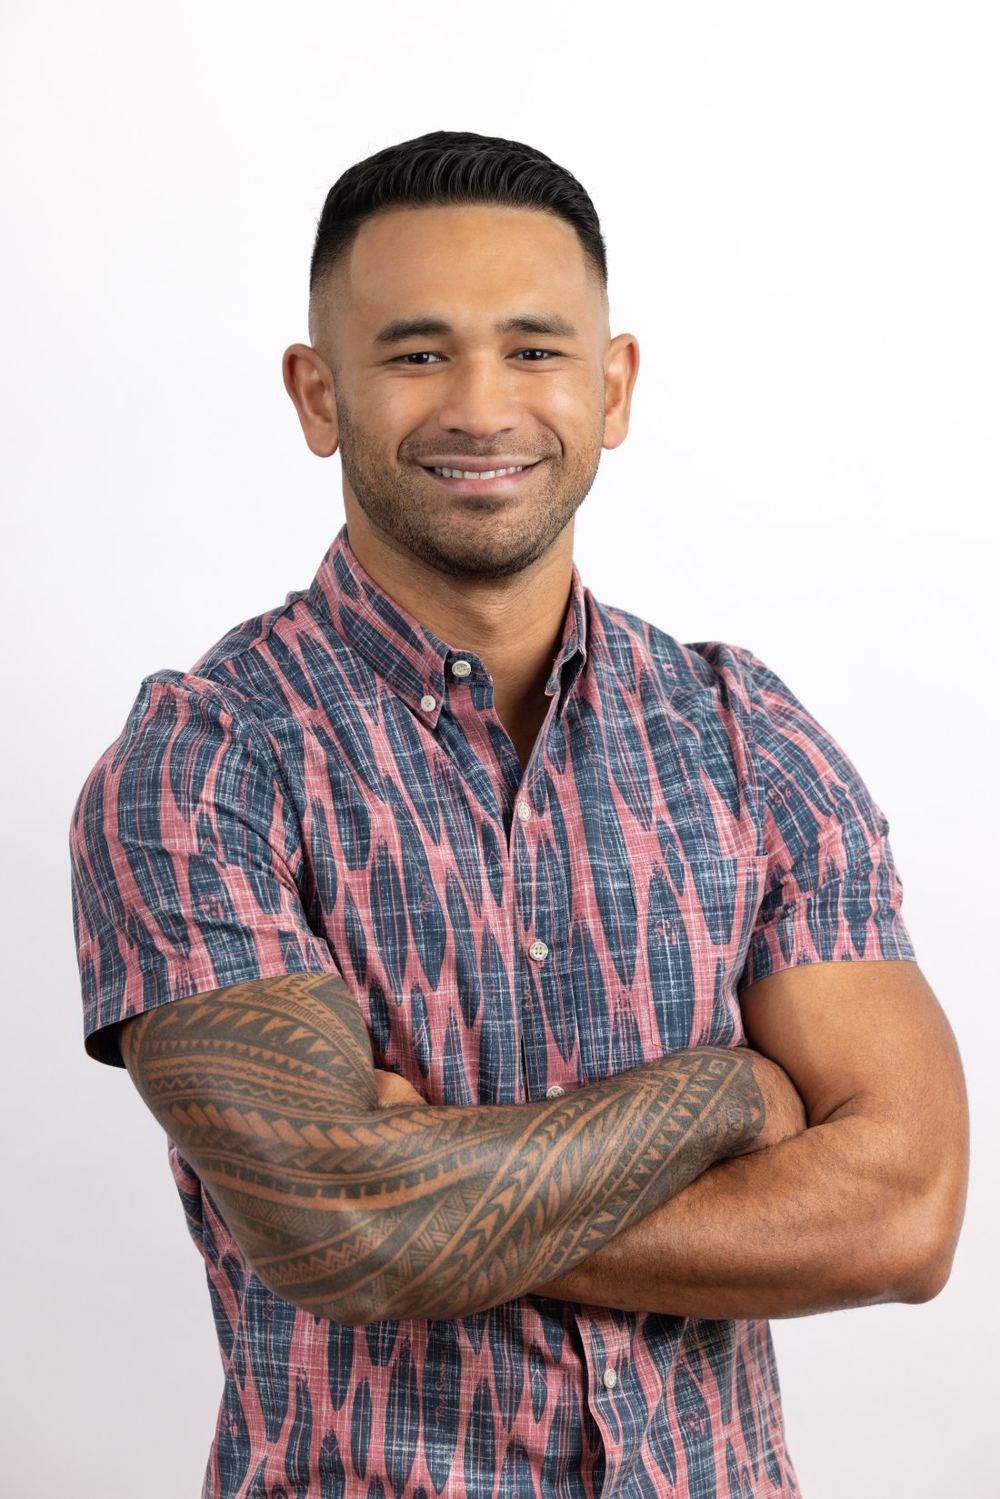
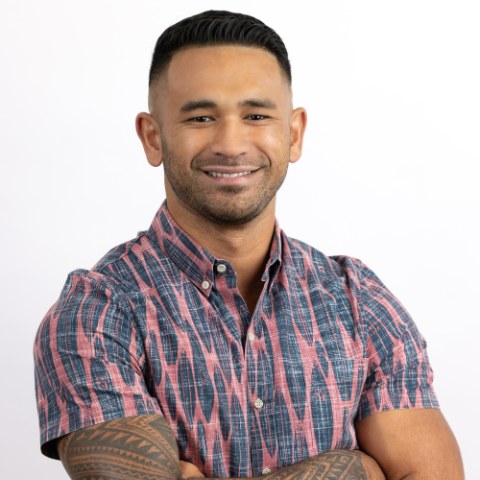
Aloha, I'm Daniel Ulu.
Born and raised in West Oʻahu, I bring deep local knowledge and a real passion for helping island families. After serving in the U.S. Coast Guard and studying political science at the University of Hawaiʻi, I began my real estate career in 2015 — and I understand firsthand what military and veteran families navigate.
When you're behind on a mortgage or underwater, it's easy to feel out of options. You're not. Over the years I've guided many homeowners through short sales, helping them move on with their dignity intact. I'll sit down with you, look honestly at your situation, and walk every step of the VA Compromise Sale process with you — from the first conversation to the day you move forward.
I value God, Family, and Business — in that order — and I strive to treat my clients like family: honest advice, total confidentiality, and exceptional service, done with aloha.
You're never negotiating alone.
I guide you locally, here on Oʻahu. The high-stakes negotiation with your lender is handled by my trusted partner, CK Capital Management — short sale specialists who do this, and only this, every single day.
They help coordinate short sale negotiations — working directly with your mortgage company, cutting through the red tape, and pushing for approval and debt forgiveness. Their services and fees are subject to separate written terms; review these before engaging them.
Every step of the negotiation — so you don't have to.
CK Capital Management is an independent partner that handles short sale negotiation. The Ulu Team and CK Capital Management are separate companies; nothing here is legal, tax, or financial advice.
Put both teams to work for you — free review →Guides for the road ahead
Plain-English reads on the questions that keep homeowners up at night — take them at your own pace.
What is a VA Compromise Sale? A plain-English guide for Hawaiʻi veterans
Understand the approval process, written debt terms, and possible effects on your future VA benefit.
Read →PCS orders and an underwater home: what military families can do
Orders don't wait for the housing market. Your real options, compared honestly — and how a short sale fits a PCS window.
Read →How a short sale affects your credit — and when you can buy again
What actually gets reported, the realistic recovery timeline, and the honest picture on your VA entitlement.
Read →The foreclosure timeline in Hawaiʻi: what happens after a missed payment
Stage by stage — late notices, the 120-day rule, the court process, auction — and the options you still have at each step.
Read →Short sale vs. foreclosure vs. deed in lieu: an honest comparison
Three doors out of an unaffordable mortgage — compared on control, credit, the shortfall, cost, and your VA entitlement.
Read →Short sale FAQs
Straight answers to what VA homeowners ask us most.
Official resources: VA mortgage assistance · CFPB short sale guide.
You don't have to figure this out alone.
A short, confidential conversation costs nothing and commits you to nothing. Let's look honestly at your options — together.
Free initial consultation · No obligation